 An insurance binder for mortgage loans is a document that provides proof of insurance coverage for a property that is being financed with a mortgage loan. Mortgage lenders require borrowers to have insurance coverage on their property to protect their investment in case of damage or loss.
When a borrower applies for a mortgage loan, the lender typically requires proof of insurance coverage before they will approve the loan. An insurance binder is a document issued by the insurance company that provides temporary proof of insurance coverage until the official insurance policy is issued.
The insurance binder for mortgage loans will typically include information about the property being insured, the coverage limits, and the effective date of the policy. The lender will review the insurance binder to ensure that it meets their requirements for coverage and will usually require the borrower to maintain insurance coverage for the duration of the mortgage loan.
Here are some reasons why you may need an insurance binder:
Closing on a new home: If you are closing on a new home, your lender may require an insurance binder to ensure that the property is adequately insured.
Purchasing a new car: If you are purchasing a new car, you may need an insurance binder to show proof of insurance coverage before you can take possession of the vehicle.
Starting a new business: If you are starting a new business, you may need an insurance binder to show proof of coverage for liability, property damage, or other types of insurance coverage.
Renting a property: If you are renting a property, your landlord may require an insurance binder to ensure that you have renters’ insurance coverage.
To get an insurance binder, you will need to contact your insurance agent or insurance company. They will typically require you to provide some basic information, such as your name, address, and the type of coverage you need. Once they have this information, they will issue a temporary insurance binder that will provide proof of coverage until the official insurance policy documents are issued.
It is important for borrowers to understand that an insurance binder is a temporary document and should not be used as a replacement for the official insurance policy. It is also important to review the insurance policy carefully to ensure that it provides the necessary coverage for the property being insured.
 Many people think that staging a home effectively is a matter of money, but there are easy ways to dress it up and make it shine that don’t come with a high cost. If you’re looking for some economical tips that will go a long way in making a positive impression, here are a few ways to get your home prepared.
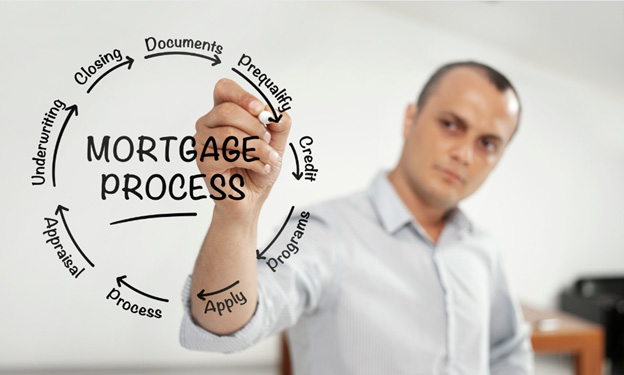 The purchase and refinance mortgage processes are similar in many ways, but there are also some important differences. Here is a general overview of how each process typically works:
 Low maintenance landscaping can be a great way to improve your home’s curb appeal without having to spend a lot of time and money on upkeep. Here are some ideas for low maintenance landscaping:
 Making major life decisions often involves a delicate balancing act. Among the most significant choices individuals face are buying a new car and purchasing a new home. Both ventures represent milestones in one’s life, bringing excitement and anticipation. However, there is a complex interplay between these two financial endeavors that can significantly impact a person’s ability to achieve their dream of owning a new home. Here are some factors to consider:
 Property taxes can be a substantial financial burden for homeowners and property owners. Each year, local governments assess the value of properties to determine the amount of property tax owed. However, these assessments are not always accurate and can result in higher tax bills than necessary. Disputing your property tax assessment is a proactive way to potentially save money and ensure you’re paying a fair and equitable amount.
 Appraisers consider several factors when valuing a house to determine its fair market value. The goal of the appraisal is to provide an unbiased and accurate assessment of the property’s worth.
 If you’re a homeowner with a mortgage, you may be familiar with the concept of an escrow account. This financial tool is designed to simplify the management of property-related expenses by combining certain costs, such as property taxes and insurance, into one account. Typically, your mortgage servicer collects a portion of these expenses with each monthly mortgage payment and holds the funds in an escrow account to cover these bills when they become due.
 Last week’s economic reporting included readings on inflation, consumer sentiment, and weekly readings on mortgage rates and jobless claims.
 Obtaining a pre-approval for a mortgage is an important step when you’re planning to buy a home. It gives you an idea of how much you can afford, helps streamline the home-buying process, and strengthens your position as a serious buyer. However, many people worry that the pre-approval process might negatively impact their credit score. In this blog post, we’ll dive into the details to determine whether or not a pre-approval for a mortgage will hurt your credit.