With the current state of affairs, it is not surprising that a majority of the releases scheduled for this week have been delayed until next week. The only notable report set to be released is the consumer sentiment report, which has been showing month-to-month declines. This has led to a very light week, with a heavy slate of inflation data scheduled for release next week. The PCE Index and CPI are both scheduled for next week.
Consumer Sentiment
The University of Michigan’s Consumer Sentiment Index fell sharply to 53.3 in March 2026, down from the preliminary estimate of 55.5 and below February’s 56.6. This places sentiment near record lows observed at the end of 2025, with declines spanning all age groups and political affiliations.
Households with middle and higher incomes, as well as those with stock wealth, experienced the steepest drops in confidence. The downturn reflects the impact of rising gas prices and financial market volatility, both exacerbated by the ongoing Iran conflict.
Primary Mortgage Market Survey Index
- 15-Year FRM rates saw an increase of 0.21%, with the current rate at 5.75%
- 30-Year FRM rates saw an increase of 0.16%, with the current rate at 6.38%
MND Rate Index
- 30-Year FHA rates saw an increase of 0.10%, with current rates at 6.10%
- 30-Year VA rates saw an increase of 0.11%, with current rates at 6.12%
Jobless Claims
Initial Claims were reported to be 210,000 compared to the expected claims of 210,000. The prior week landed at 205,000.
What’s Ahead
CPI and PCE Index data is set to release the next week along with other notable delayed releases such as unemployment data.
 Major life transitions often coincide with real estate decisions. Marriage, divorce, expanding families, career changes, or retirement can prompt the desire for new space. Purchasing during periods of change requires clarity, patience, and strategic planning to ensure the property supports your next chapter rather than adding stress.
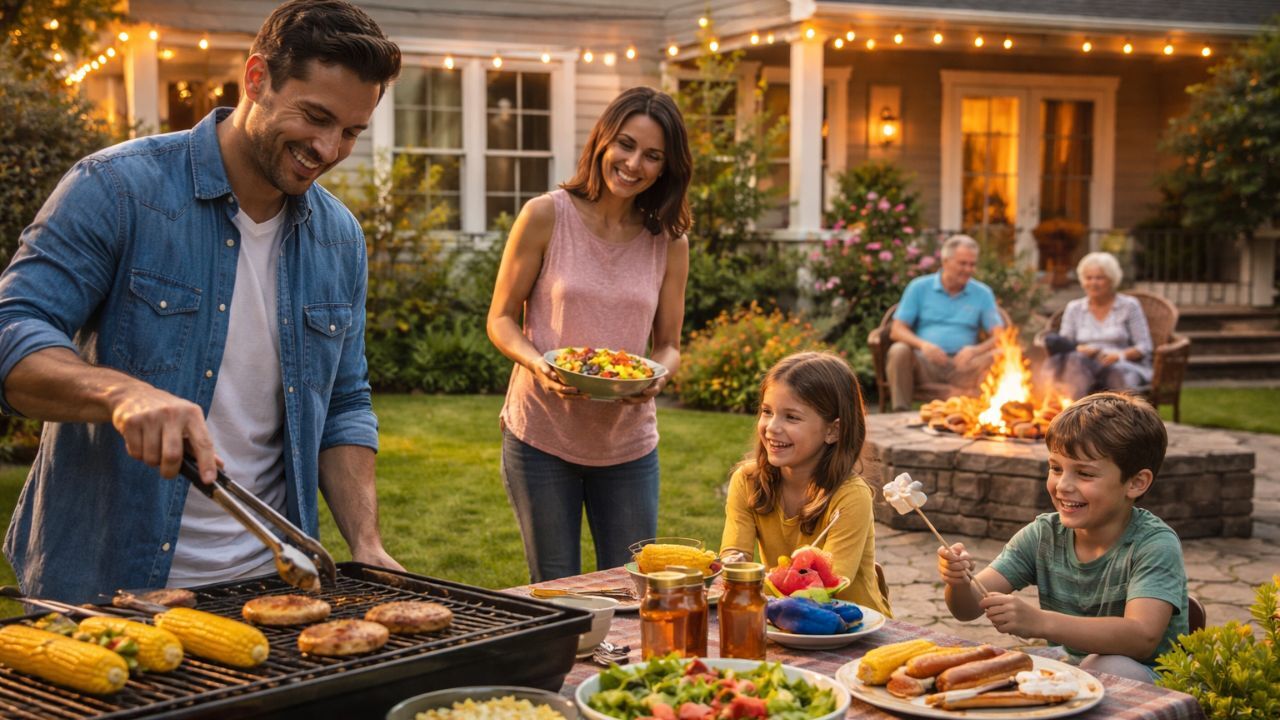 Homeownership often marks the beginning of a new chapter for families. Beyond financial stability, owning a home creates a consistent setting for memories, routines, and milestones. The impact extends far beyond property value. It influences how traditions form, how children experience holidays, and how family identity develops over time.
 Relocating to a new city can feel both exciting and disorienting. Whether driven by career opportunity, family needs, or lifestyle change, moving markets involves more than comparing property listings.
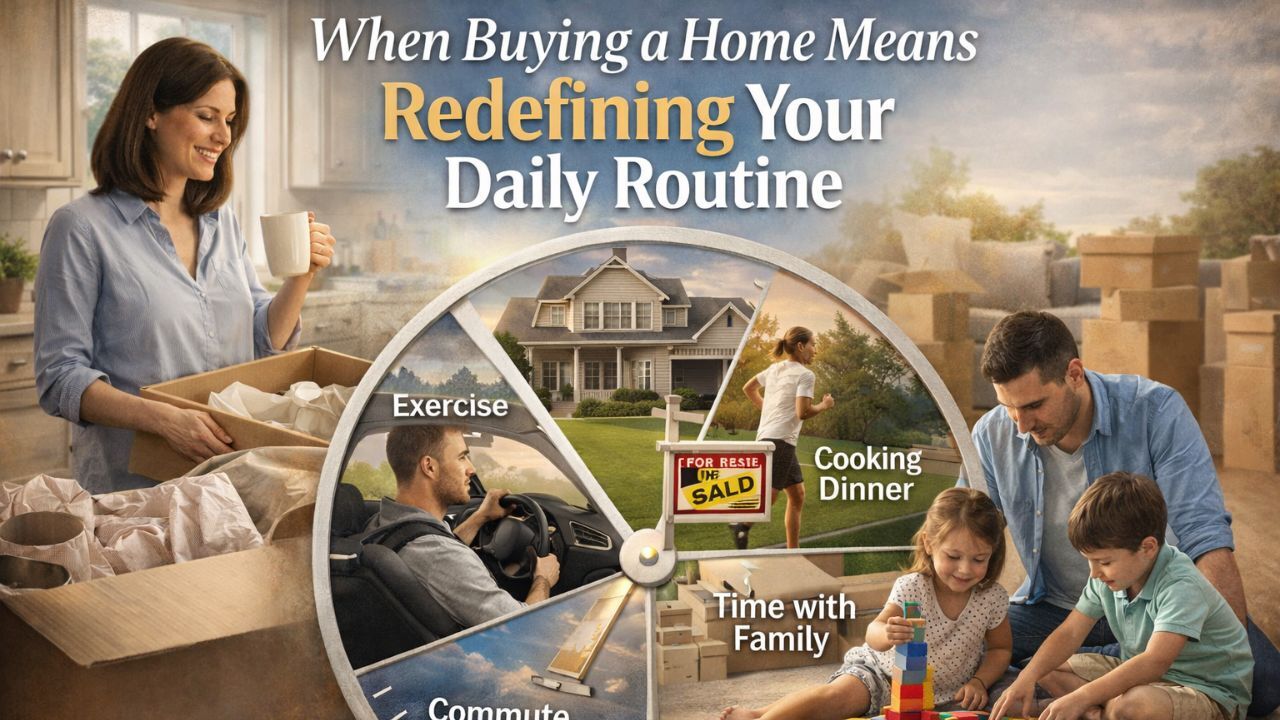 Buying a home is often framed as a financial milestone, but its deeper impact is felt in daily rhythm. A move changes commutes, morning patterns, school drop offs, weekend habits, and even how families gather in the evenings. The decision to purchase is not simply about square footage. It is about reshaping how life unfolds each day.
 Buying a fixer upper can seem like an opportunity to build equity quickly. Lower purchase prices often attract buyers who believe renovations will unlock value. While that can be true, many underestimate the true cost of repairs, time, and disruption. A fixer upper requires careful evaluation before committing.
 Home inspection reports often intimidate buyers. Detailed lists of findings can appear overwhelming, even when most items are minor. The purpose of an inspection is not to identify a perfect property. It is to highlight maintenance, safety, and system conditions so buyers can make informed decisions. Understanding how to interpret these reports prevents unnecessary anxiety.
 Buyers quickly form impressions about whether a home feels fairly priced. Even before reviewing detailed data, perception influences interest levels. When a property feels overpriced, buyers may skip showings entirely or submit lower offers. Understanding what creates that perception allows sellers to adjust before losing momentum.
 Receiving an offer is exciting, but the negotiation phase determines the true outcome of a sale. Many sellers focus only on the highest price, overlooking terms that can significantly affect net proceeds and timeline stability. Successful negotiation requires understanding of both financial and contractual components. Strategic evaluation protects leverage and strengthens final results.