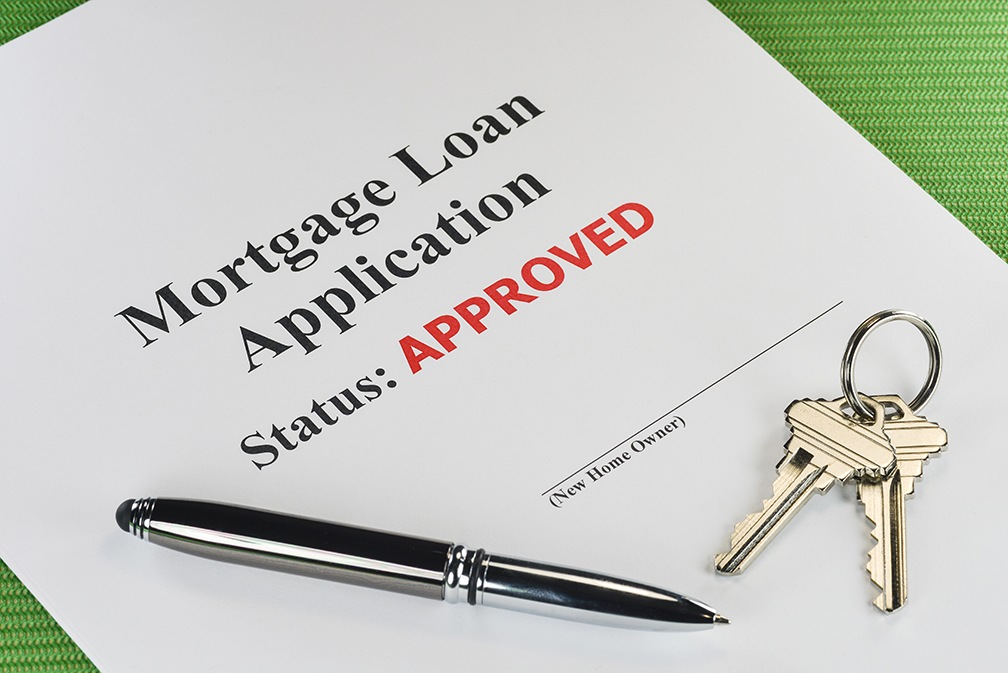
 Are you in the market for a new home? If you are going to rely on mortgage financing to cover some of the purchase cost, you will need to start the application process as soon as possible. However, what if you just need to know how much you will be able to borrow so you can start finding homes in your price range?
Let’s take a quick look at the difference between being ‘prequalified’ and ‘preapproved’ for mortgage financing.
The Process Starts With Prequalification
The first step in obtaining mortgage financing is to speak with a mortgage professional to get prequalified. After sharing some quick information about your financial assets, income, and any debts, your advisor will share a range of financing options and amounts that you may qualify for. Prequalification is typically done free of charge and either in person or over the phone.
Note that your mortgage lender will not be doing any digging in the prequalification stage. There’s no credit check and no hard look at your assets. Don’t get too excited if you are prequalified for a large mortgage as you will still need to be approved.
Once You Are Preapproved, You Are All Set
Preapproval, on the other hand, is a firm commitment to access to a certain level of mortgage financing. Your mortgage lender will require a variety of information to get an idea of your financial situation, your current and future employment, your level of risk and more. Once they have a good idea of how much mortgage you can afford, you will be provided with a conditional commitment letter. This letter outlines how much the lender is willing to offer to you as well as other vital information like your mortgage loan interest rate.
Speed Up The Process By Preparing Beforehand
Finally, it is worth a mention that you can speed up the mortgage process by having all of your application paperwork ready before the initial meeting. Gather up your most recent income tax returns, pay stubs and bank statements. If you have investments or other financial assets, document those. You will also want to be up front about any outstanding debts that you are paying off. The more prepared you are, the faster the application and pre-approval process will go.
Have you found the home of your dreams? Contact your local real estate professional to get started.
 Is it time to move on from your house, townhouse or condo? If a sale is in your near future, you will want to start looking for a professional selling agent or broker to help manage the process. Let’s take a look at our quick and easy guide to finding the best real estate agent to handle your home sale.
 Home builders had less confidence in housing market conditions in September. In the aftermath of Hurricanes Harvey and Irma, builders worried that ongoing shortages of construction labor and materials would worsen. NAHB Chairman Granger MacDonald said that concerns over labor and building materials were “intensified,” but said that builder confidence was expected to return to high readings once rebuilding is underway.
 Are you tired of scouring the internet, trying to find the secret recipe for whatever will take stains out of your carpet? And the irritating annual steam cleaning ritual where your whole home is soaking wet for a couple of days? Ugh. If your old carpet has you down, it might be time for a change. In today’s blog post we’ll share five great reasons why you’ll want to make the switch from carpet to hardwood floors.
 Last week’s economic readings release included reports on inflation, core inflation retail sales and retail sales excluding autos. Consumer sentiment, along with weekly readings on mortgage rates and new jobless claims were also reported.
 Have you been considering a mortgage for your next home purchase? As with any loan or financial product, there are a variety of fees and costs you may incur in the process of closing your mortgage. In today’s post, we’ll explore a few of these potential fees and the situations in which you may encounter them. Let’s get started!
 Are you thinking about selling your home? If so, you may be weighing the pros and cons of working with a professional real estate agent. Let’s take a quick look at three great reasons why you won’t want to handle the sale yourself.
 Whether you’re tired of renting, need more space or want to make an upgrade, buying your first home is the solution. However, if you have never participated in the market before it can be a bit daunting at first. Let’s explore a few useful tips that are helpful for first-time homebuyers who are new to the process of buying real estate.
 Whether you’re just out of college, recently married or simply haven’t jumped into the market yet, buying your first home is an exciting prospect. It can also be an expensive one, which is why most people will take out a mortgage to help finance the cost.
 Last week’s economic news was slim due to the Labor Day Holiday. Scheduled releases included the Fed’s Beige Book Report and weekly readings on mortgage rates and new jobless claims.